Friday, December 8, 2017

How much have I earned and lost in 2017?

How much have I earned and lost in 2016?

My objective for 2017 was to maintain my existing portfolio and receive $10,000, and achieve a stock to cash (exclude emergency funds) allocation ratio of 50:50. I met my target. It is also a milestone for me to have finally reached $1,000/month of passive income. It has been 14 years since I dreamt of hitting this target. It had been a combination of work hard to increase my earned income, to learn how to pick stocks, and to cultivate patience and will-power.

Income was $11,800 (this is based on received, will be $12,800 if based on ex-date), which was largely due to increase in portfolio and better bank interest rates for interest income from Bank of China 2.5%, UOB One 2.43%, Hong Leong Finance 1.7%, CIMB Fastsaver 1%, Singapore Savings Bonds 1.1%. I picked up $29 worth of coins (about 100 coins, of which 40 coins are 5 cent coins, which is still $2). Every coin adds up.

Average dividend yield is 4.56% (based on ex-date). After some rebalancing this year and using retirement calculators, I decided that my objective for 2018 is to increase my average yield by 0.5%, and then maybe another 0.5%/year for another 2 years, to 6%, but I will reassess this at the end of 2018. This will need to be supported by increasing REITs to 50% of my portfolio. Currently, the ratio is about 23%, I will implement this by rebalancing and capital injection at the right prices over 3 years, from 23% -> 33% -> 43% -> 50%.

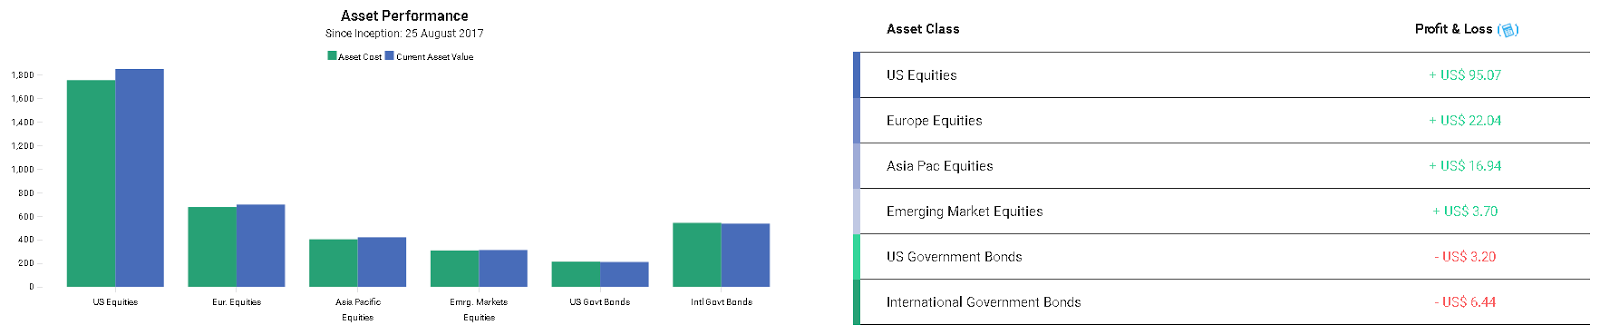
I also started investing in Vanguard ETFs through Autowealth, adopting a dollar cost averaging approach, but I select which day of the month to deposit my money to buy, hoping to catch low points in a month. I started with $5,000 in Aug 2017, and contribute $400/month. It is currently returning an insane annualised yield of 15%, which I don't believe is sustainable, hence I am taking it slow and steady.

Unrealised profits which is nice to see but cannot eat:
Autowealth = S$260
Singapore Stocks = $20,000
Although we are not at the end of the year yet, I don't foresee much variation over the next few weeks. I will update again if there is a sudden market crash or something.

Objective for 2018: Increase REITs by 10%, increase portfolio yield by 0.5%, increase income to $14,000.

Chart of humble beginnings
Lifetime accumulated dividends and interest, net of losses = $49,000

Portfolio income "methodology": Assuming that I continuously invest $36,000/year or $3,000/month,
In 3 years, accumulated dividends and interest = $100,000, $1,600/month
In 7 years, accumulated dividends and interest = $200,000, $2,200/month
In 10 years, accumulated dividends and interest = $300,000, $2,700/month

Compounding is awesome. Every coin adds up.

Thursday, December 7, 2017

What did I buy in Nov 17?

QAF I bought more shares when prices hit $1.10. As there was price weakness after the oversupply of pork in Australia, I decided to spread purchases over a few months to get a better spread. If prices were to remain at this level, I may add more.

Other shares that I had been watching are:

  • SIA Engineering
  • Comfort Delgro
  • Singapore Press Holdings
  • ST Engineering

I had no luck at the RE&S IPO.

No bargains in the market, so I will continue to save up and wait.

Wednesday, November 8, 2017

Stock Review: M1

Earlier on when M1's price was hovering around $2, I briefly calculated a price tag of $1.75 before I will do a more detailed review of M1's financial report. I just assumed no dividend at year end, hence whole year dividend of 11 cents, -20% discount to factor in -20% YoY decline, divide by 5% yield and arrived at 11 x 0.8 / 0.05 = $1.76.

On 11 Aug 17, the lowest price was $1.705. Prices have been hovering around $1.78, but I think it's time I write a review. High tide floats all boats and the market is at a high tide now so I am ignoring market prices.

In M1's 3Q2017 report, the concluding sentence was "Based on current outlook and barring unforeseen circumstances, we expect a decline in net profit after tax for the year 2017."

"Net profit after tax declined 4.8% year-on-year for third quarter and 13.9% year-on-year for 9 months ended 30 September, 2017. This is in line with our previous outlook statement." -- From here, I think it's safe to assume that it will decline 20% YoY.

9M2017 EPS  = 10.9 cents. assuming straight line decline, annual EPS should be 14.5 cents.

Assuming a payout ratio of 90%, which is the lower end of M1's historical payout ratio, dividend for 2017 = 13 cents.

Assuming 2 more years of consecutive 20% YoY decline,
2018 EPS 14.5 x 0.8 = 11.6 cents
2019 EPS 11.6 x 0.8 = 9.28 cents

Apply payout ratio of 90%, 9.28 x 0.9 = 8.352 cent

5% yield = 8.352 / 0.05 = $1.67
6% yield = 8.352 / 0.06 = $1.39

This is the extent of the margin of safety you can get at lower prices.

Two things were neatly hidden in plain sight which a casual reader will probably miss out.

1. Debt appeared to be downplayed. "Gearing ratio" is a technical term which casual readers will miss. It is calculated by dividing Total Debt by Total Equity. Total Debt is how much the company has borrowed. Total Equity is how much capital and retained earning over the years. When retained earnings is high, it shows that the company has been successful in accumulating wealth. If the company always pays out 100% of earnings as dividends, then $0 goes into Equity. Imagine you have $10,000 in your savings and I lend you $60,000 as unsecured lending (not backed by anything like your branded handbag or gold ring), your gearing ratio is 6 times, and I run a very high risk of not getting my money back because you only have $10,000. 

Interest coverage ratio shows the ability of the company to pay interest expenses with earnings - the higher the better - they were in a better position in 2016 because earnings were higher. Imagine you have a fixed interest expense, and your salary is decreased 20% YoY, then you will find it harder to repay. Usually you need to pay the interest to keep the loan active so that your bank will not force you to sell your assets to raise money.
9M2017 Page 20 of 22 Gearing and Interest Cover
However, this will probably not concern you if you are a shareholder of Starhub because Starhub's gearing ratio is much higher at 6 times. Just for comparison, I had calculated Singtel's gearing ratio too. Just as an illustration, REITs have a gearing ratio of around 30% to max 45%, so you read it in REITs presentation slides as 0.3x or 0.45x.
Accurate as at date of data extraction on 8/11/17
2. There is also a CAPEX item - spectrum rights - that will likely be recorded in Q4 and beyond. The report did not mention how they will fund the purchase, be it cash or loan. When reconciled with the cash flow statement, nothing has been paid yet. 

9M2017 Page 19 of 22 - CAPEX and Commitments
9M2017 Page 3 of 22 Cash Flow Statement - spectrum rights not paid yet
Taking its debt and committed CAPEX into consideration, I am sitting out and will probably review again when the price hits $1.39.

Monday, October 30, 2017

Am I a High Risk Taker?

Risk assessment questions are often biased. Take the below question from Autowealth as an example. I have nothing against them by the way. I consented to be categorised as a high risk taker.
I understand that markets are at times volatile. If my investment portfolio loses 10% of its value, I would:


If I choose Buy more, my risk appetite is assessed to be higher. In most cases, buying more is always a representation of someone who takes high risks. In order of risk appetite, a low risk taker might sell everything.

However, there are two aspects to this. In reality, do these people really buy more or they just choose buy more as a textbook answer? Do they sell everything or hope for prices to recover? 

The typical question is about a down trend scenario. Let us now think about an up trend scenario with the same scenario options. My portfolio has increased by 10%, if I buy more, am I a high risk taker?

From my observation, when prices drop by 5%, most people will not buy more, neither will they sell parts or everything. When prices drop by 10%, most will not buy more, instead, some might sell parts or everything. When prices drop by 20%, most will do nothing. When prices increase by 5%, most people will do nothing. When prices increase by 10%, most will sell, especially if prices had been depressed for some time. When prices increase by 20%, more will buy and not sell anything.

Many surveys and friends have classified me as a high risk taker. In theory and in practice, that is what I do:
Down trend of a stock - I buy more
Up trend of a stock - I do nothing most of the time. Sometimes I sell 25% of my stock's volume to rebalance if prices have risen to a price that I feel it's too high.

For illustration, between Aug 2015 to Jul 2016, I spent at least 100k buying stocks in a year. I felt poorer and poorer every month because prices continued to fall or remained low. I still remember spending 30k in one particular month. For comparison, I only spent about 20k this year. Everyday I wished that I had more money to buy. I asked my broker to increase my buy quota to 40k because I couldn't submit orders to buy queues. I allocated different budget pots for different price drawdown %, so I was at 70-30 stock to cash allocation when the market was just about -20%. When stock prices started rising, I was relieved because I could finally start saving up again, which shows that I am not that high a risk taker? I see myself taking calculated risks, i.e. I know that I have factored in sufficient margin of safety. I know I had done my best evaluation based on all the known information available when I made the decision. My priority is also income investing because that is a double safety net for me -- a margin from income and a margin from capital gain.

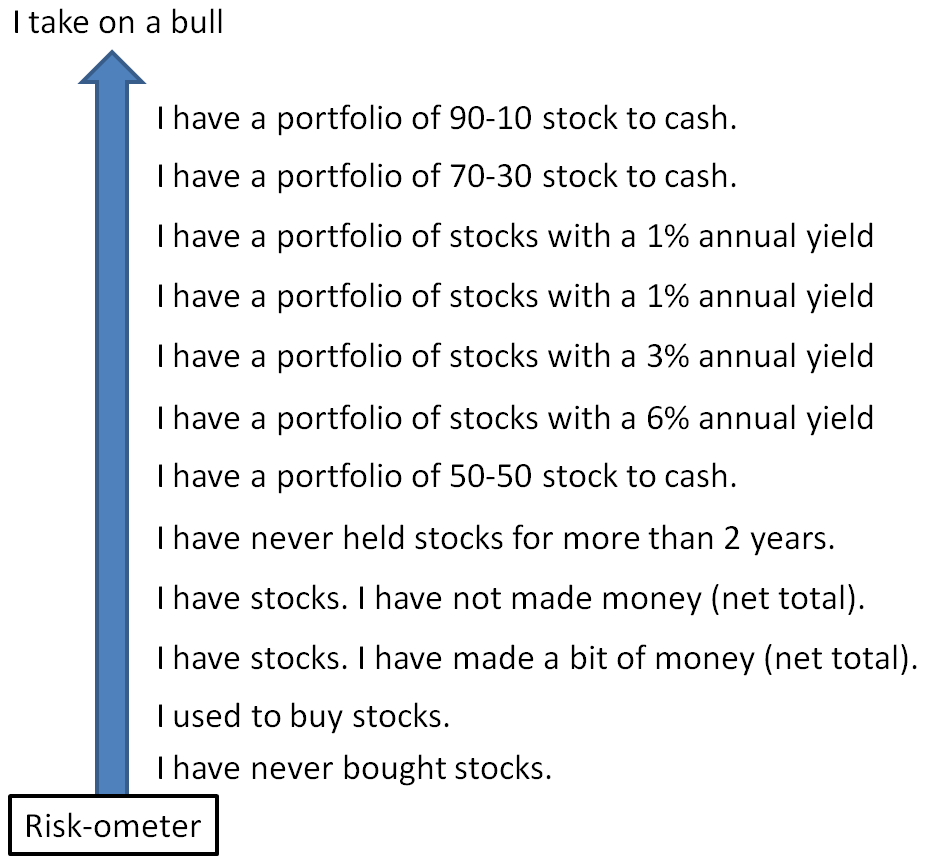
My risk-ometer
I usually hover around 50-50 stock to cash to feel safe. My financial advisor advises 80-20 investment to cash, investment including ETFs, unit trusts and endowment funds. She said I am taking on more risk by keeping 50% cash. Obviously, we don't have the same definition of risk. Similarly, everybody's definition is slightly different. Hence to really assess the person appetite for risk, maybe that one question is probably a good proxy after all, even if it's just a textbook exercise.

Friday, October 27, 2017

What did I buy in Oct 17?

SIA Engineering (covered in previous post) I didn't add further as the price stablised at $3.20.

Cache Logistics 18 for100 Rights Issue. I also applied for excess rights with UOB (don't think it matters) and got a surprisingly good deal -- 42.5 to 100. Cache has been slightly disappointing, but I am banking on it's long leases and an 8% yield is still good.

UMS Holdings 1 for 4 Bonus shares. To be honest, I didn't even know that there was a bonus issue until I saw the share price fell 15% and it said XB. Free shares, so it's good.

I also decided not to buy more ETFs (via Autowealth) this month as I will be prioritising warchest over investments. As of now, warchest : vested capital ratio is about 40:60. I also channelled cash into CPF retirement accounts (markets were suddenly high so I decided to sit out and transferred $10k to my daughter's MA so that I can have an extended MA if I need it in future) As I have met the FRS for CPF SA, I was also assessing if I should repay the accrued interest that I owe my future self. In the end, I decided that I might be able to get a better return than 2.5% OA, so I will continue to work on my portfolio and build up my warchest. I believe in focus -- do one thing at a time. Multi-tasking doesn't work when it comes to saving money.

The recent run-up in stock prices is not entirely driven by fundamentals hence its making me feel a little uneasy. Steep gradients are a testament of my earlier (good) decisions, but I had also started thinking about my upper end targets for overvaluation. For now, SG stocks prices are still far from being overvalued (especially those whose PER are <=12).
Portfolio returns (from stocks cafe)

Saturday, October 21, 2017

AutoWealth and I

I thought I will also share a bit about why I decided to try out Autowealth. There are just 3 companies offering similar robo-advisory services in Singapore. Autowealth is one of them, the other two are Smartly and StashAway. I have nothing against the other two, but I was drawn to AutoWealth and I believe in fate.

Earlier this year, I had a chance to learn more about their business model from the "brain" behind the formula used by AutoWealth -- Tai Zhi. It was at an exhibition booth at Innovest Unbound and their booth was empty so I went over to ask a few questions.

I had my doubts about the company's sustainability

  • The marketing was a little bit "smoky" because anybody who had bought shares post Aug 2015 would have made decent gains, so I wasn't impressed when they marketed the 5-6% returns after a year.
  • The "brain" is honest. His IT guy - the guy who coded his brain out and did the portal - is down-to-earth. I had a fleeting thought that these guys might get conned by someone.
  • The fees are so low SGD 18 platform fee/year regardless of the number of transactions. Imagine every customer does weekly buys... lol even monthly buys, I don't know how to earn. On top of that, they charge 0.5% of Asset Under Management (AUM), which is really like a charity business.
  • Marketing hasn't been agressive, unlike their competitors, but it shows that they are down-to-earth (again) and watch their bottom line.
  • Shares are held in a custodian, so they can be easily "knocked out" of business and the customer don't need them anymore.
I went to research a bit more about the ETFs they recommended and I decided to sign up after a few months. The ETFs recommended have really really low expense ratios. I don't really care about the ETF performance because prices fluctuate and there is nothing much to compare between ETFs other than the expense costs.

Here are some screen shots of how it looks like. I don't know if I can share it but it was one of the burning questions I had before signing up. (Seeing how down-to-earth they are, I decided that I will help them with their marketing lol...)

There is a portofolio summary.

There is a composition chart to show you that they really buy according to the ratios they showed you when you signed up.

Shows you how each ETF is doing too.
Top-up history -- this is important and it's there
There are many other screens, but I don't use them.

I have no doubt about their passion to bring investment to the masses. I still have my doubts about the company's sustainability, but I am not buying shares in AutoWealth, so it doesn't matter. If AutoWealth shuts down tomorrow, the shares are held with Saxo Capital, Power of Attorny will cease, and I have the Saxo not-so-sexy portal to still see the market prices, but I will probably have to pay much much higher transaction fees. In the meantime, all I can do is to do a little bit of charitable marketing, in hope of increasing their sustainability. I will definitely increase my AUM with them to about 10% of my portfolio when US equity prices moderate a bit. For now... I am happy to see just 1% of my portfolio grow at a crazy 0.5% per week.

List of ETFs invested:
  1. Vanguard Total Stock Market Index Fund ETF Shares (VTI) expense ratio 0.04%
  2. Vanguard European Stock Index Fund ETF Shares (VGK) expense ratio 0.10%
  3. Vanguard Pacific Stock Index Fund ETF Shares (VPL) expense ratio expense ratio 0.10%
  4. Vanguard Emerging Markets Stock Index Fund ETF Shares (VWO) expense ratio 0.14%
  5. Blackrock iShares 7-10 Year Treasury Bond ETF (IEF) expense ratio 0.15%
  6. Blackrock iShares International Treasury Bond ETF (IGOV) expense ratio 0.35%

Thursday, October 5, 2017

What did I buy in Sep 17?

SIA Engineering
Prices continued to fall, especially after the announcement that it will be removed from the ST Index from 1 Oct. On 4 Oct, prices gapped down on news that JP Morgan was selling its 38.8M stake in SIA Engineering. I bought more at $3.30 and $3.20. $3.20 was the previous low in the Aug 2015 "flash crash". Strong balance sheet and monopoly nature of business are the main reasons for me to buy. I will buy more if prices fall below $3.05, another 5% to cover a year of dividends.

SPH
I staked my money at my mouth and bought at $2.76 and $2.62. Prices fell to a low of $2.54 but did not hit my next queue at $2.48. Recently prices have been hovering around $2.70 so I am not taking any further action. I was also comparing SIA Engineering and SPH, and preferred to place more money in SIA Engineering because of its strong balance sheet, doesn't mean that SPH is a better stock because it is still in the ST Index. Did you know that the co-owners of the ST Index are SGX and SPH? Will SPH be removed from the index? I don't know.